Financial Data Analysis Project
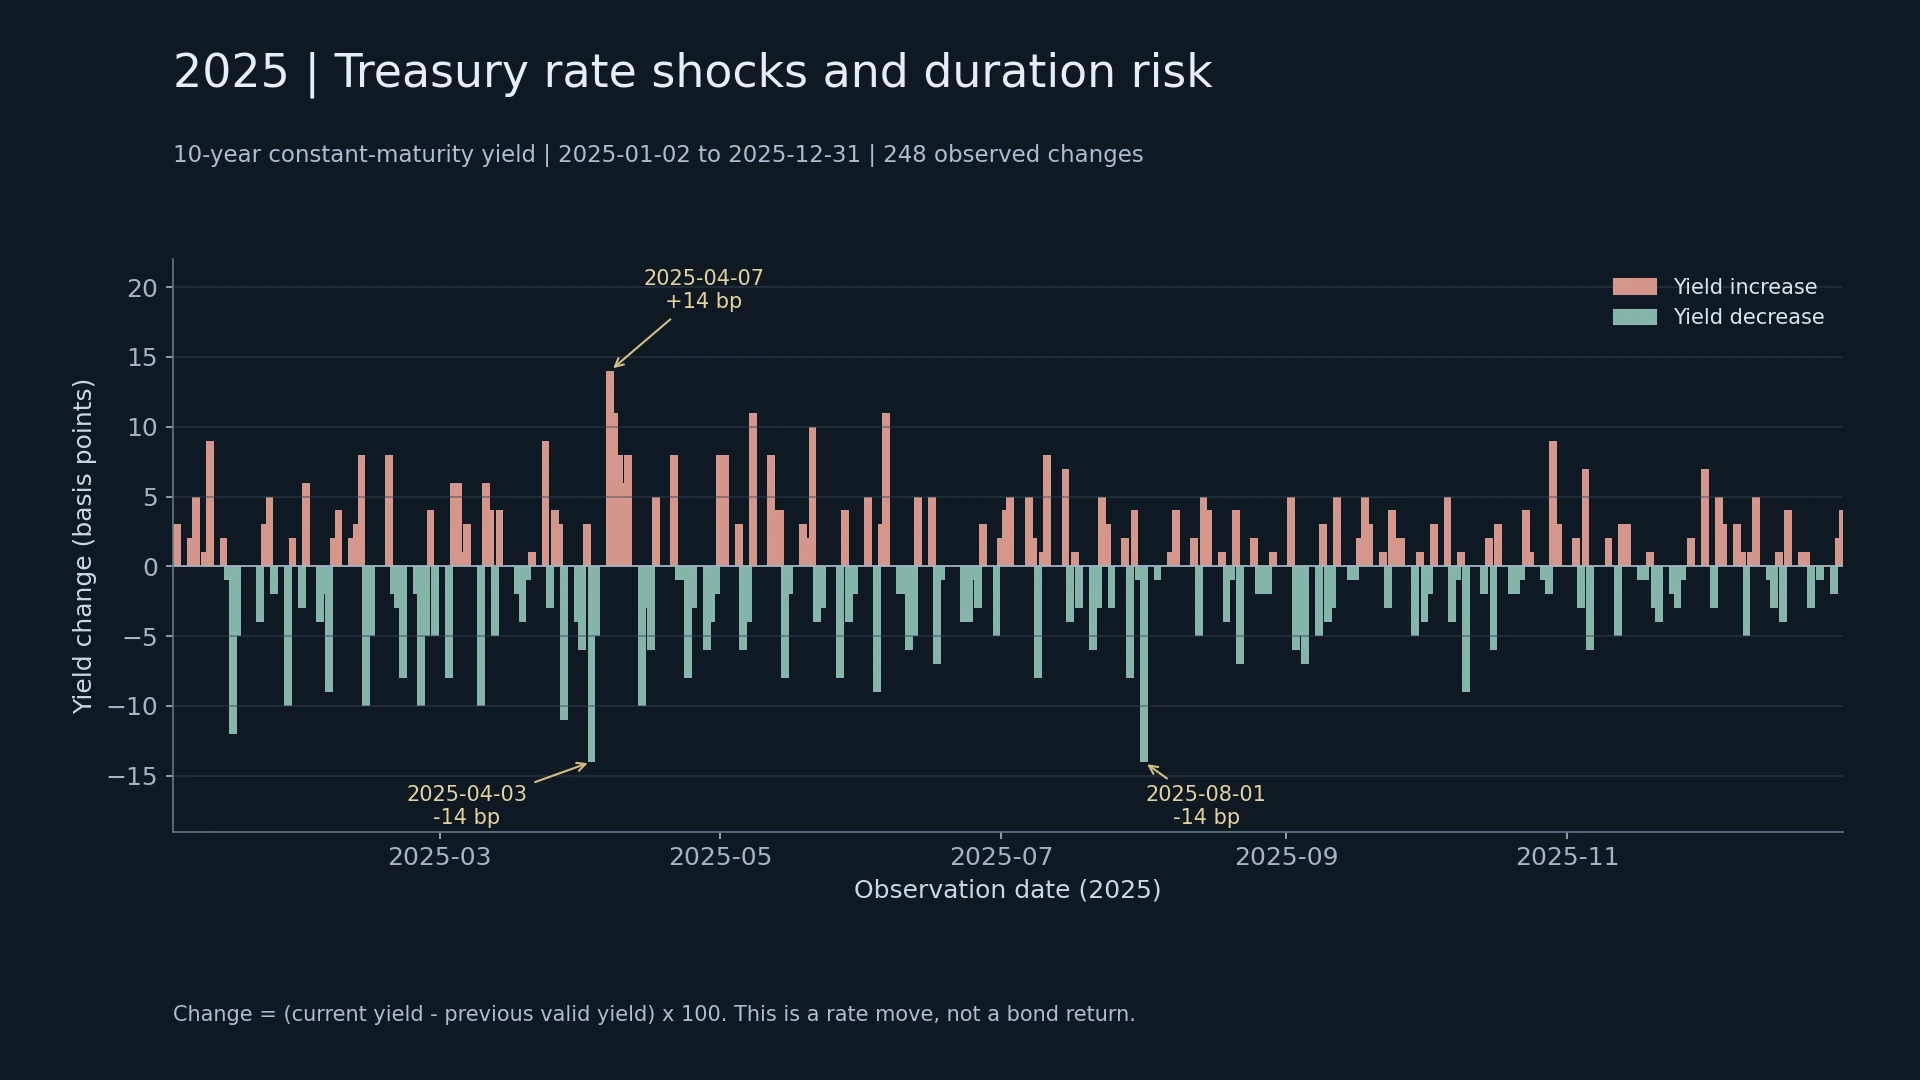
2025 Bond duration and interest rate risk: from real shocks to DV01
Taking the real treasury bond 91282CLW9 as an example, we review the auction price, calculate duration and DV01, and test the revaluation error under interest rate shocks.

2025 Term Spread: Change Path and Observation Boundary
Split the contribution of the long and short ends to the term spread, analyze the different sources of curve steepening, and distinguish between portfolio risk and bank net interest margin.
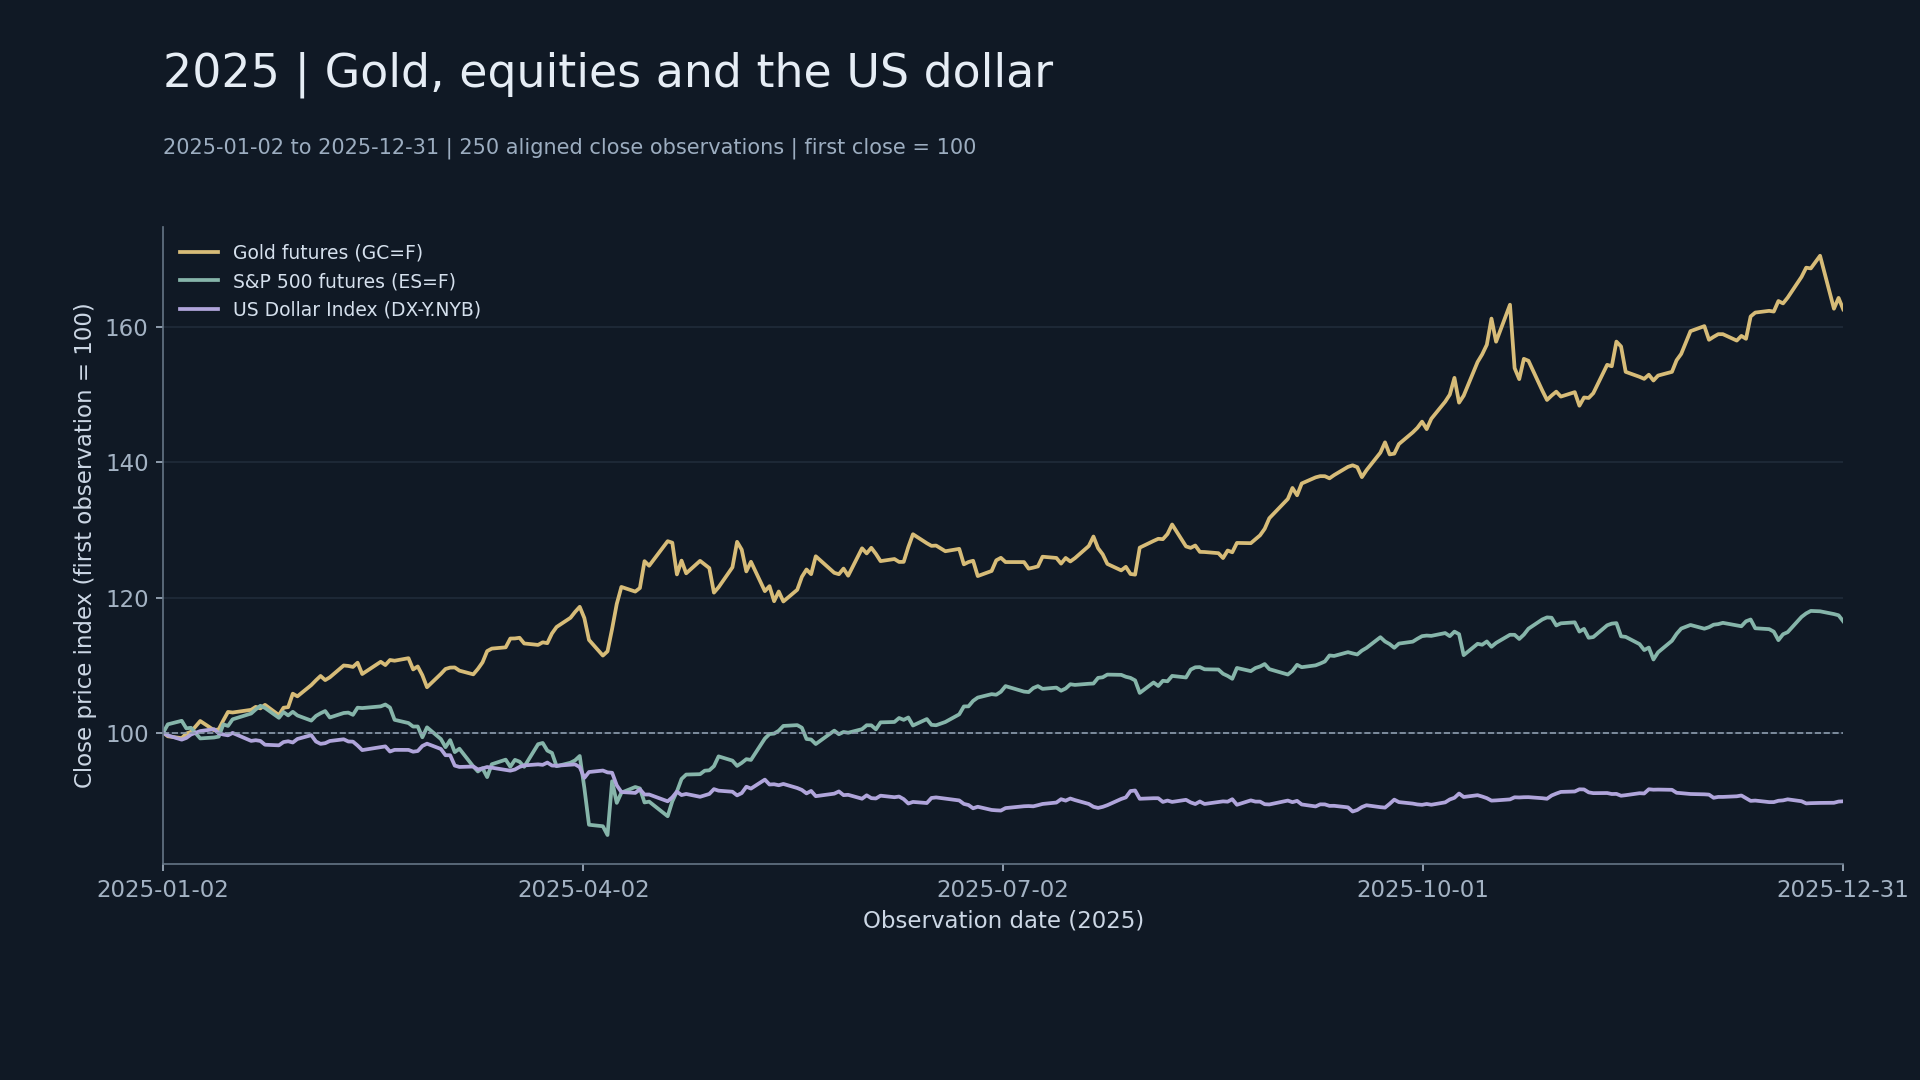
2025 Multi-asset allocation research: returns, correlations and risk diversification
Compare the full sample and short-term correlation, test the cross-asset performance of the equity index during the stress period, and clarify the applicable boundaries of the allocation conclusion.
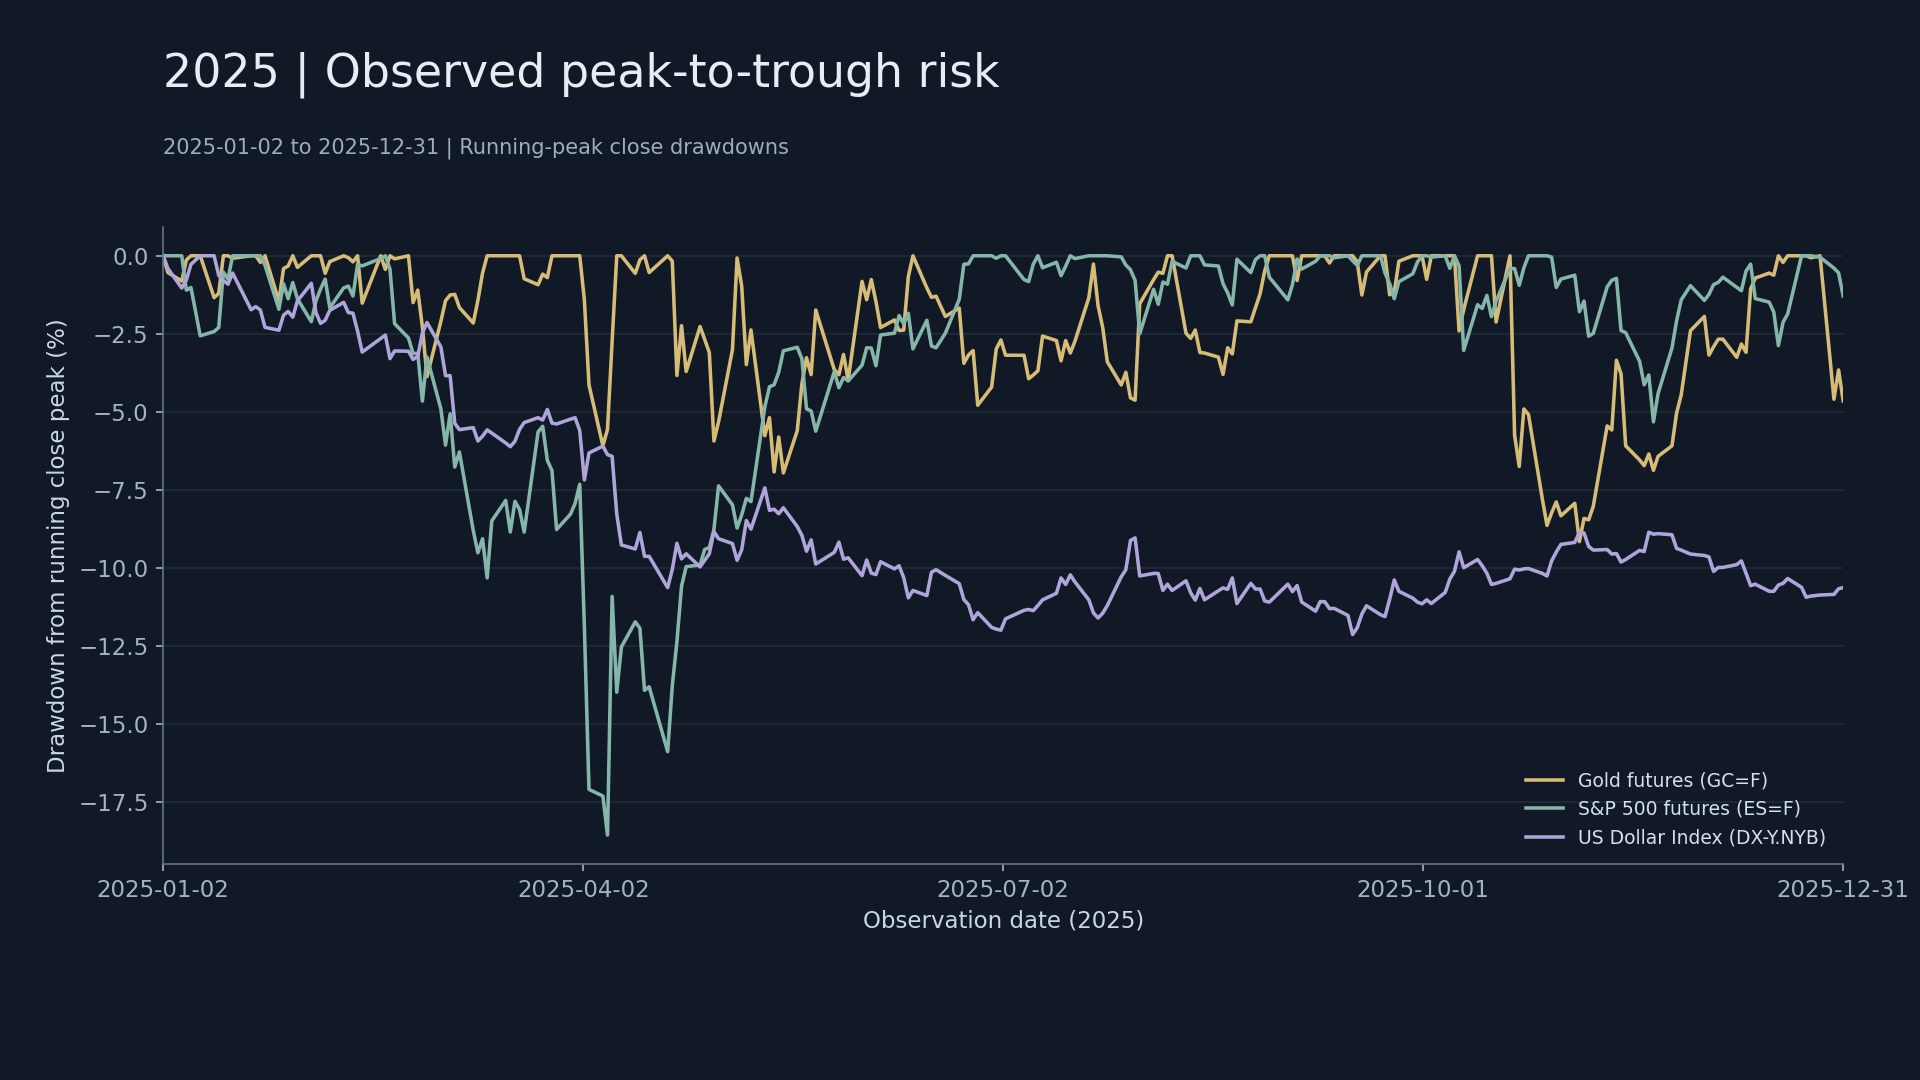
2025 actual drawdown vs. scenario amounts
Identify actual peaks and valleys and recovery dates, analyze drawdown recovery requirements, and measure nominal exposure, account equity, and scenario gains and losses separately.

2025 U.S. Treasury Yields: Changes in Short-End and Long-End
Compare short-term and long-term yield levels on a quarterly basis and distinguish the different impacts of interest rate direction, yield curve shifts and cash flow valuation.